


Meta Connect Just Started and the Stock Is Already at a 52 Week High
Meta Connect Just Started and the Stock Is Already at a 52 Week High
Vandita JadejaFri, September 25, 2026 at 2:00 PM UTC
0
Fritz Jorgensen / iStock Editorial via Getty ImagesQuick Read -
Meta (META) earns a BUY rating with an $842 price target as shares hit 52-week highs, up 37% in a month on Muse AI ad momentum.
Meta's 41% operating margin dwarfs Alphabet's (GOOGL) 32%, while Snap's (SNAP) 9% ad growth and negative P/E reinforce Meta's premium valuation.
Meta's capex guidance in the range of $130 to $145 billion and its Q2 free cash flow collapse to $784 million are the primary risks threatening the bull thesis.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
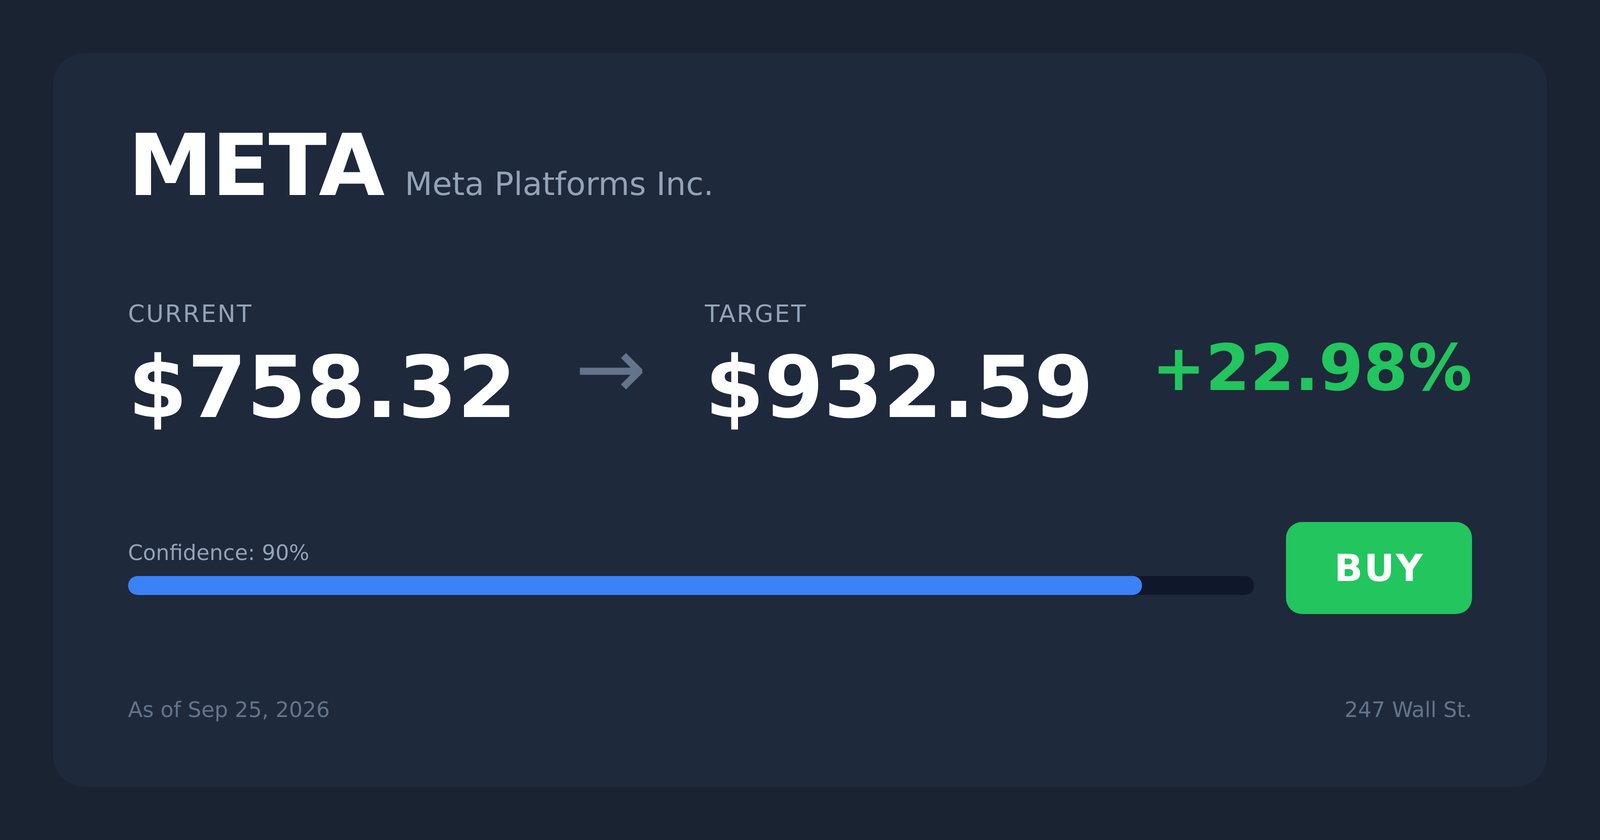
Meta (NASDAQ:META) opened its 2026 Connect developer conference today with shares at $754.78, up 37.35% in the last month. Our 24/7 Wall St. price target is $842.43, implying 13.1% upside over 12 months.
We rate the stock buy with high confidence, driven by AI-powered ad monetization and a glasses lineup flagged as a fast-growing consumer electronics category.
24/7 Wall St. Price Target Summary
Metric
Value
Current Price
$754.78
24/7 Wall St. Price Target
$842.43
Upside
13.1%
Recommendation
Confidence Level
90%
META Price Target — 24/7 Wall St.A Muse-Powered Rally Into Connect
Meta is having its best month in 13 years on enthusiasm around the Muse AI assistant. The stock is up 12.69% in the last week and 14.62% year to date, nearing its $758.54 52-week high as CEO Mark Zuckerberg takes the Connect stage.
Instacart signed on as a Muse partner, reinforcing the enterprise AI narrative. Q2 2026 delivered $60.8 billion in revenue, up 28%, though EPS of $6.18 missed the $7.22 consensus after $2.4 billion in legal charges and $1.2 billion in severance.
META Price Scenario — 24/7 Wall St.Why Bulls See a Breakout Above $880
The bull thesis rests on AI monetization. Zuckerberg said on the Q2 call that "on a dollar basis, our ads business is reporting faster year over year revenue growth than any other company's reported ad business."
Advantage Plus is already running at a $75 billion annual run rate, Meta AI daily interactions jumped 60% after the Muse Spark integration, and glasses sales are exceeding expectations.
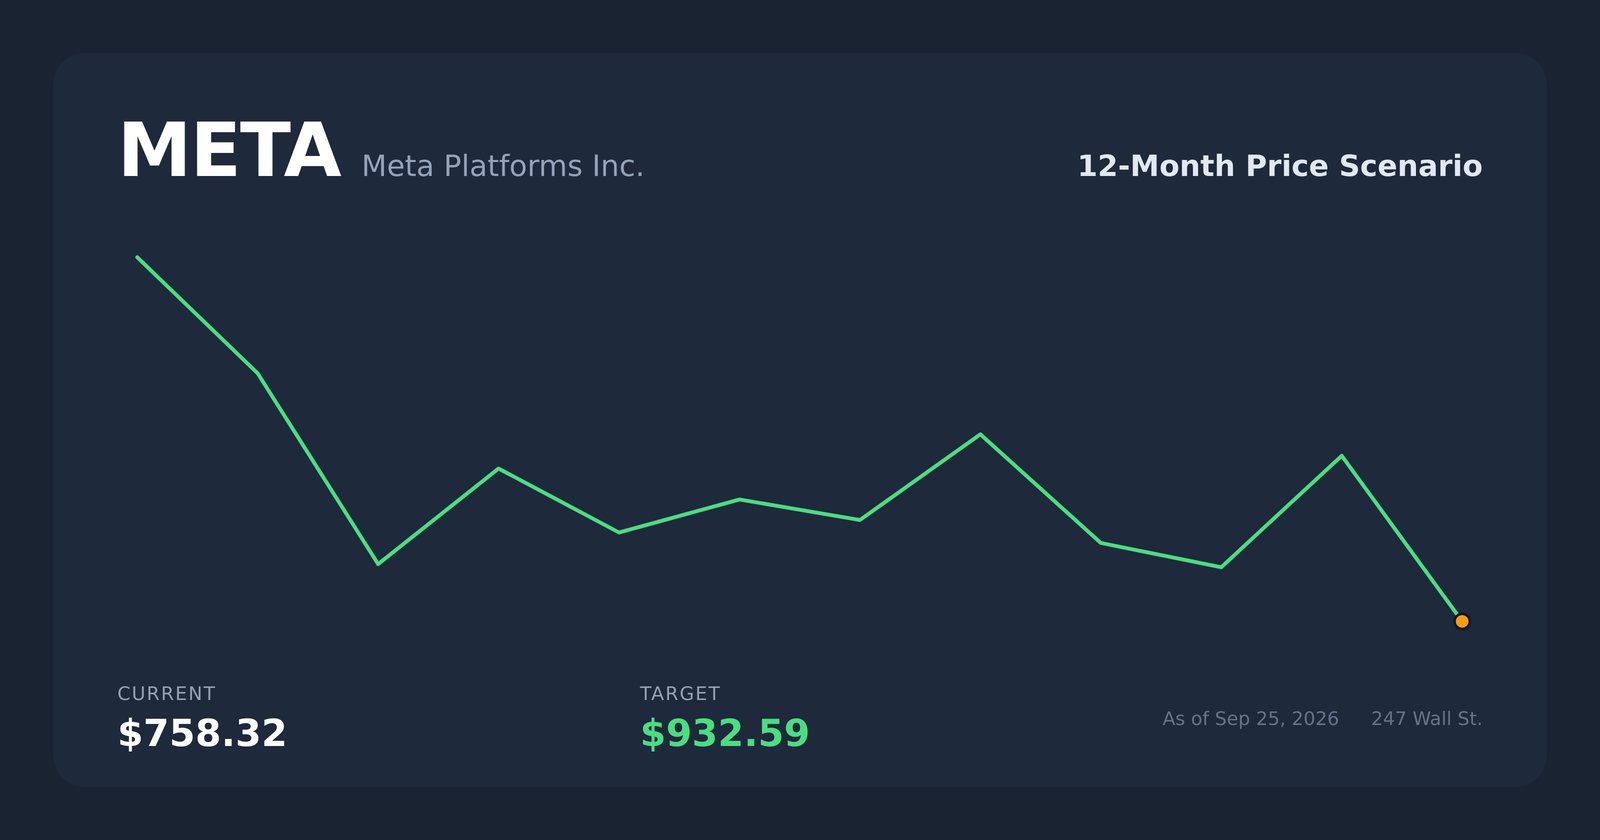
Our bull scenario points to $879.67, an 18.1% return, on the assumption Connect unveils a bigger glasses lineup and enterprise Muse deals like Instacart continue to close.
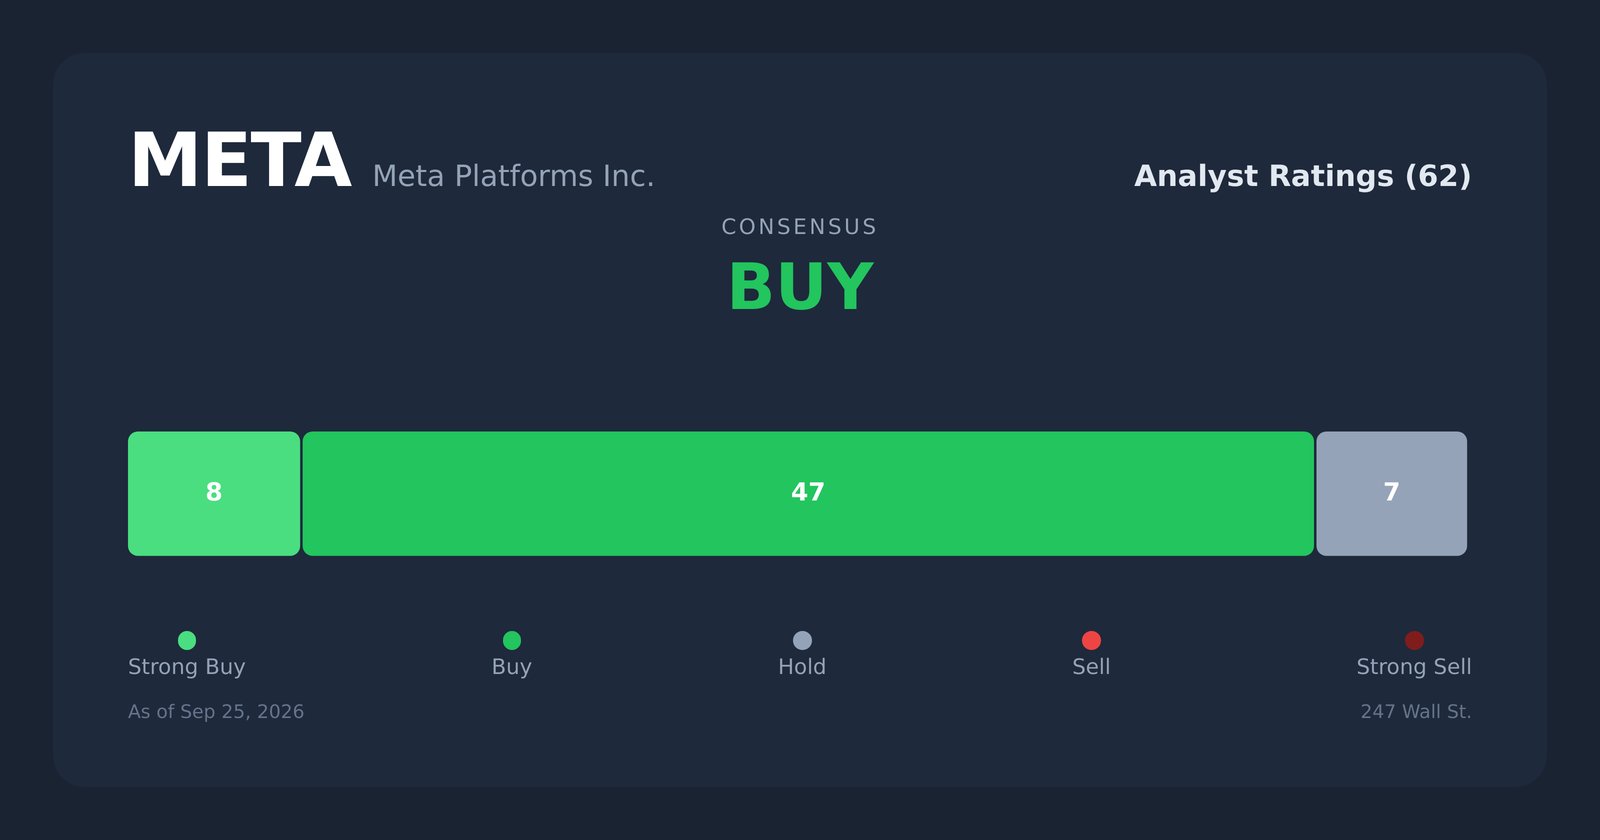
META Analyst Ratings — 24/7 Wall St.What Could Go Wrong
Capex is the counterweight. Meta guided 2026 spending to $130 to $145 billion, free cash flow collapsed to $784 million in Q2, and long-term debt now sits at $83.66 billion. Forbes flagged today that the new AI may not scale to justify the spend. U.S. youth-safety trials also carry material-loss risk.
Advertisement
Bulls counter that excluding legal and severance, Q2 operating income would have grown 9%, and that the infrastructure buildout is a moat that justifies the spend (the power, cooling, and networking suppliers riding that same buildout are the subject of a free report you can grab here). Our bear case still shows just $729.93, a manageable 2% drawdown.
How Meta Compares to Alphabet and Snap
Alphabet (NASDAQ:GOOGL) is the cleanest comparable on ads and AI infrastructure. It trades at a 16 P/E versus Meta's 28, with Google Cloud growing 82% in Q2. On that comparison our Meta target looks aggressive, but Meta's 41.44% operating margin trumps Alphabet's 32%, justifying a premium.
Snap (NYSE:SNAP) is the AR-glasses counterpoint via its SPECS launch. Snap grew ad revenue just 9% in Q2 and remains unprofitable with a negative P/E. The gulf makes Meta's premium look earned rather than stretched, and reinforces our buy.
Meta Price Prediction 2026-2030
The 24/7 Wall St. price target of $842.43 reflects a buy at 90% confidence. The tipping factor is Meta's proven ability to convert AI into ad dollars faster than any peer.
The bull case strengthens if Connect delivers a credible consumer glasses roadmap and enterprise Muse traction. The thesis weakens if Q3 capex guidance climbs again or if the youth-safety trials produce a nine-figure settlement.
Year
24/7 Wall St. Price Target
2026
$762.57
2027
$844.89
2028
$905.80
2029
$997.24
2030
$1,063.66
These projections assume Meta continues executing on AI-driven ad monetization and glasses adoption. Meaningful upside or downside could come from enterprise Muse revenue scaling or from regulatory outcomes in the pending youth-safety trials.
Help Avoid These 13 Retirement Mistakes Before They Derail Your Future
One investment mistake could create big risks for your retirement. Many investors make the same critical errors: being too conservative, making big bets on “sure things,” or paying excessive fees. Any of those blunders can endanger your hard-earned savings.
Now you can learn the mistakes even experienced investors make (and ways you can sidestep them before it’s too late) with this new guide: 13 Retirement Mistakes and How to Avoid Them from Fisher Investments. (sponsor)
Contact editorial@247wallst.com for any questions or corrections.
Source: “AOL Money”
